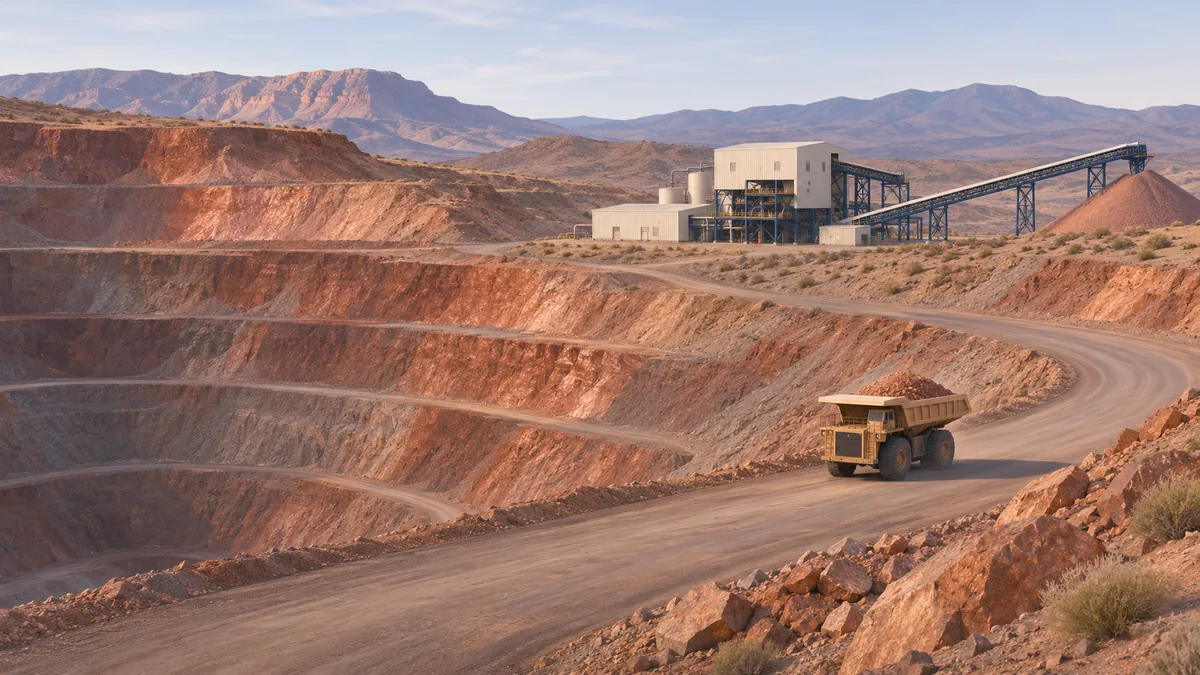
Freeport's $4.5 billion copper expansion joins a crowded budget
Bagdad could produce more copper at lower long-term unit costs. Its funding schedule overlaps other projects and Grasberg's recovery.
Beyond the headline.
Inside the numbers.
Ticker Byline
Freeport news and analysis covering copper production, Bagdad and Grasberg, capital spending, cash flow, debt and shareholder returns.
Freeport-McMoRan Inc. produces copper, gold and molybdenum through operations in the United States, South America and Indonesia. Its shares trade on the New York Stock Exchange as FCX, and it reports on a December 31 year-end. Bagdad is wholly owned. Freeport consolidates PT Freeport Indonesia, or PTFI, despite owning 48.76%, so group production and cash include other shareholders' interests.
On November 4, 2026, the board approved a $4.5 billion expansion and modernization of the Bagdad copper and molybdenum operation in Arizona. Initial production is targeted for mid-2030 after approximately 3.5 years of construction.
The project is expected to add about 225 million pounds of annual copper output and 12 million pounds of molybdenum. Long-term total copper output would exceed 400 million pounds annually. Management expects about a 20% reduction in unit net cash costs, supported by scale, automation and molybdenum by-product revenue. Its break-even case assumes about $4-per-pound copper and $20-per-pound molybdenum.
Planned funding is 20% in 2027, equivalent to roughly $900 million, 30%–35% in 2028, and the balance in 2029–2030. The $4.5 billion estimate was already disclosed in the August quarterly report. October's presentation said it excluded $200 million of early work already incurred through September.
The October capital outlook called for $4.4 billion of group spending in 2026 and $5.2 billion in 2027, with Bagdad early work already included in the later year. Freeport says it will incorporate the approved investment into an updated outlook. The project is classified as discretionary under its financial policy.
| Measure | 2025 | 2026 |
|---|---|---|
| Revenue | $6,972 | $7,546 |
| GAAP operating income | $1,972 | $2,353 |
| GAAP net income attributable to common shares | $674 | $1,174 |
| GAAP earnings per share | $0.46 | $0.81 |
| Adjusted earnings per share | $0.50 | $0.88 |
Adjusted earnings exclude specified costs and gains, principally current idle-facility and restoration costs associated with the Grasberg recovery. Copper sales fell to 749 million pounds from 977 million, while the average realized copper price rose to $6.54 per pound from $4.68. Higher commodity prices supported earnings despite lower sales volumes.
First-nine-month operating cash flow was $5.524 billion, versus $4.942 billion, including $699 million of current insurance proceeds. Capital spending was $3.236 billion, versus $3.489 billion. The group paid $650 million of common dividends, bought back $305 million of shares through its program and distributed $625 million to noncontrolling shareholders.
At September 30, consolidated cash and equivalents were $4.335 billion and carrying debt was $9.398 billion. Net debt including PTFI's downstream processing debt was $5.063 billion. The financial-policy measure excludes $3.237 billion of that project debt, leaving $1.826 billion. The company estimated parent-available cash at about $3.3 billion after minority interests and withholding taxes.
Freeport's $3 billion revolver and Cerro Verde's $350 million facility were undrawn and run through May 2031. PTFI's separate $1.75 billion revolver had $250 million drawn and was extended in September to September 2031. Scheduled 2027 note maturities include about $700 million at PTFI and $600 million at the parent.
The October annual sales forecast was approximately 3.0 billion pounds of copper, 649,000 ounces of gold and 93 million pounds of molybdenum. The October presentation projected copper sales of 3.7 billion pounds in 2027 and 4.1 billion in 2028, including noncontrolling shareholders' shares.
Grasberg is expected to reach about 80% of capacity by mid-2027 and approach full capacity by year-end. Its smelter restarted in late August 2026. Kucing Liar requires an estimated additional $4 billion through 2033, with its start-up schedule under review. Leaching initiatives have a current annual run rate of about 220 million pounds of copper, with a 300-million-pound target for 2027.
In May 2026, Freeport completed a $107 million purchase of additional Cerro Verde shares, increasing its existing ownership from 55.08% to 55.66%. The Indonesian agreement announced in February for mining rights beyond 2041 remains subject to the amended license and formal process, including its conditional future ownership terms.
Bagdad could produce more copper at lower long-term unit costs. Its funding schedule overlaps other projects and Grasberg's recovery.