Tandem's Mobi can go tubeless. The sales test comes next year.
U.S. clearance brings a new option for the current insulin pump. Tandem now has to turn it into adoption and recurring sales.
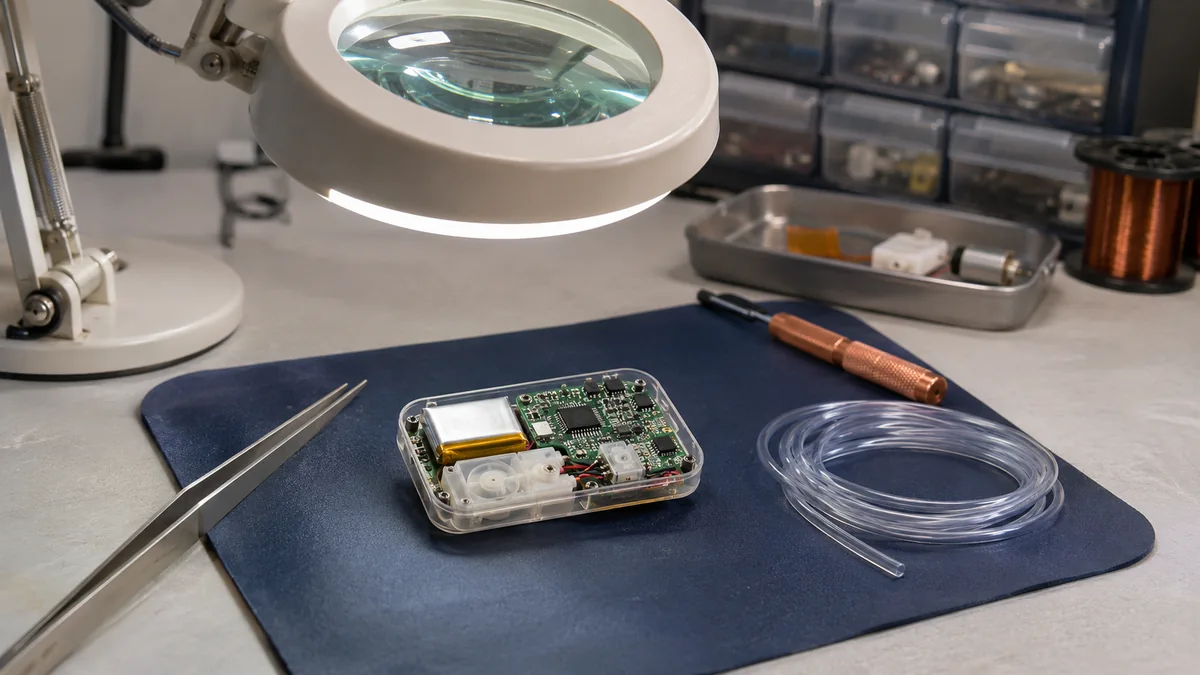
Tandem has cleared an important hurdle for its Mobi insulin pump: a new cartridge and infusion set can turn the existing device into a tubeless system. The company says it received U.S. regulatory clearance on November 12 and plans a full U.S. commercial launch in the first half of 2027.
That brings a new wearing option closer to customers. For investors, the next test is whether the launch helps Tandem bring in users and expand recurring supply sales as its payment model changes.
An upgrade to the current pump
The cleared option works with the current Mobi pump. It is separate from the next-generation, smaller Mobi patch pump Tandem lists in its development pipeline.
The infusion set, the component attached at the delivery site, is cleared for up to seven days of wear. The insulin cartridge is cleared for three days of use.
Tandem had submitted the tubeless application in the second quarter. The November filing moves that project from regulatory review to launch preparation.
The revenue mix is already changing
Research by Ticker Byline shows that supplies and other revenue provided all of Tandem's U.S. sales increase in the September quarter. That category rose to $107.7 million from $90.8 million, while pump revenue slipped to $83.4 million from $84.8 million.
U.S. pump shipments nevertheless rose to nearly 23,000 from more than 20,000. Revenue per shipment is changing as Tandem expands a pharmacy-based, pay-as-you-go model that removes the large upfront pump reimbursement. The company expects more revenue per customer over four years, with a greater reliance on recurring supplies.
This makes adoption and continued supply purchases useful measures of the new option's commercial progress. The clearance filing does not give a sales estimate for the new option.
A smaller operating loss, with cash still going out
Worldwide third-quarter sales rose 14% to $283.7 million. The operating loss narrowed to $2.4 million from $22.9 million, while the net loss was $7.1 million.
For the first nine months, operations used $24.4 million of cash and capital spending used another $15.0 million. Tandem held $443.1 million in cash, equivalents and short-term investments at September 30, following a convertible-note issue earlier in the year.
The November 5 outlook kept annual sales at $1.065 billion to $1.085 billion. A U.S. product launch planned for 2027 is a later commercial milestone. What matters next is how many customers choose the option and what that adds to the recurring business. The Tandem company profile follows the financial results, payment transition and product timeline.