Core & Main's sales are rising. Its profit target is shrinking.
Preliminary results point to lower margins as transportation costs, expansion spending and softer construction markets weigh on earnings.
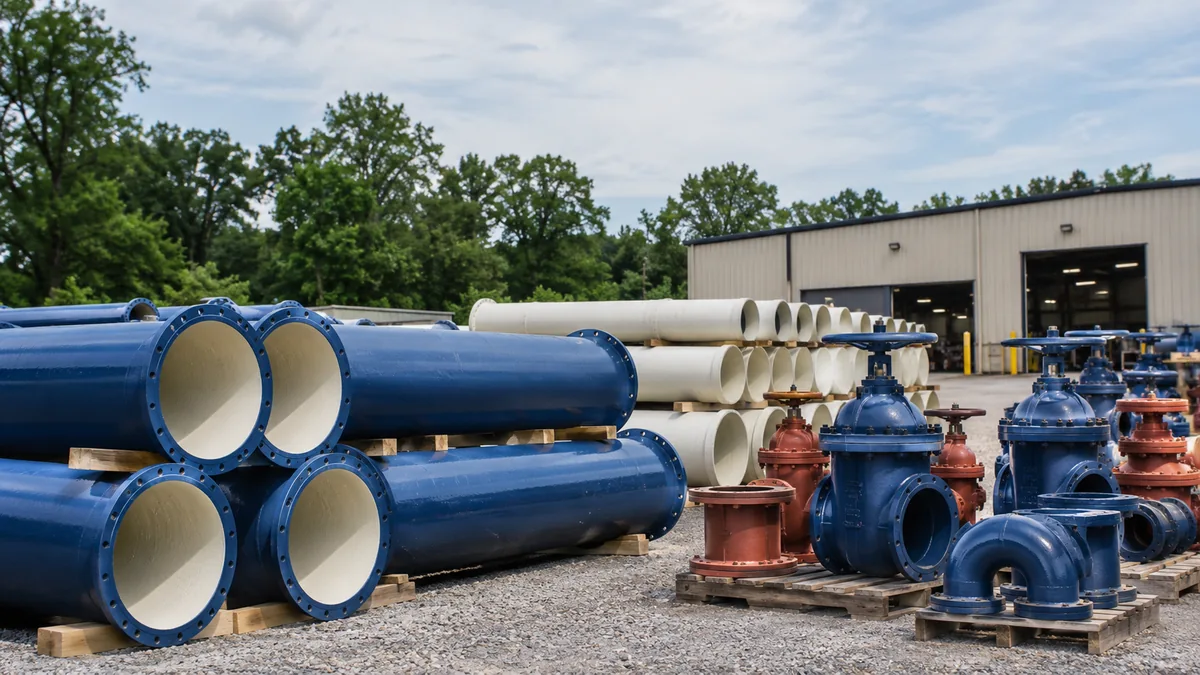
Core & Main expects its latest quarterly sales to be about 3% higher than a year earlier. It is also trimming its annual adjusted profit forecast as transportation costs, new-location spending and weaker construction markets weigh on the return from those sales.
The water-infrastructure distributor published preliminary results on November 10, ahead of its full report scheduled for December 8. It supplies pipes, valves and other products used in water, wastewater, storm drainage and fire protection.
More sales are leaving a smaller margin
Research by Ticker Byline shows that even the strongest margin implied by Core & Main's preliminary ranges falls below the year-earlier quarter. We compared estimated adjusted EBITDA with estimated sales across the disclosed ranges.
| Measure | 2026 estimate | 2025 |
|---|---|---|
| Sales | 2,120 to 2,130 | 2,062 |
| Net income | 128 to 140 | 143 |
| Adjusted EBITDA | 267 to 275 | 274 |
The implied adjusted margin ranges from about 12.5% to 13.0%, against 13.3% a year earlier. EBITDA measures profit before interest, taxes, depreciation and amortization. Core & Main also removes stock compensation and selected acquisition and other expenses from its adjusted figure.
The gap is therefore wider than the headline sales growth suggests. Preliminary net income is lower across its entire range, while adjusted EBITDA could be slightly above or below last year's result.
The sales forecast holds. The profit ceiling does not.
Core & Main kept its annual sales forecast at $7.8 billion to $7.9 billion. Its adjusted EBITDA range narrowed to $950 million to $960 million, from $950 million to $980 million reaffirmed in September.
The company says municipal demand remains stable. Residential lot development and light commercial activity have been softer than expected. Higher transportation costs and investment in new locations also affected preliminary quarterly profit. Eight new locations have opened this year.
Acquisitions and buybacks keep moving
Core & Main completed three acquisitions: stormwater specialist Southwest Stormwater Solutions in September, pipe-and-fittings distributor Gajeske in October, and Canadian utility-solutions provider KTI in November. Together, the acquired businesses have more than $250 million in annual revenue. That figure is their combined business size, rather than sales already added to Core & Main's latest quarter.
It also repurchased $171 million of shares during the quarter, bringing the year's purchases to about $428 million. Around $240 million remained authorized for future repurchases.
The distributor is still investing and returning cash. The revised outlook shows that sales growth and acquisitions have not removed pressure on profitability in the existing demand environment. December's full results will add the cash-flow statement behind those decisions.
The Core & Main company profile records its forecast history, preliminary quarter and completed acquisitions.