Archrock's $415 million power deal leans on profits still to come
The purchase adds long power contracts and a growth pipeline, but the quoted valuation uses forecast earnings and includes projects awarded verbally.
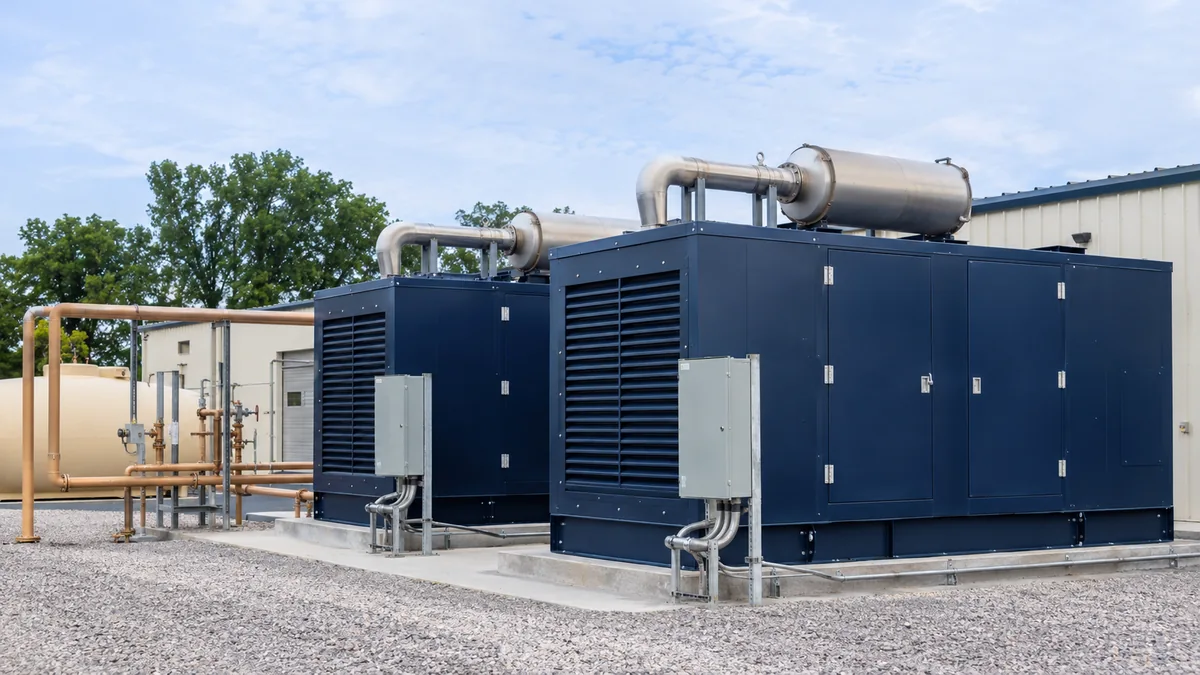
Archrock is expanding from natural gas compression into power generation with a $415 million base cash deal for HiVolt. The price is being presented against earnings expected in 2028, making the quality of the project pipeline central to the investment case.
HiVolt supplies on-site electricity to customers that cannot wait for a grid connection. Archrock expects the acquisition to close in the first quarter of 2027 and add to earnings per share immediately.
What sits behind the 2028 earnings target
HiVolt has more than 80 megawatts of contracted power capacity today. Archrock forecasts $70 million to $75 million of adjusted EBITDA in 2028, a measure that removes interest, taxes, depreciation, amortization and selected other costs.
About 70% of that forecast is supported by operating sites and opportunities described as contracted or awarded. Research by Ticker Byline shows that the latter category includes verbally awarded projects: the investor presentation's definition is broader than signed contracts alone. The presentation does not separate the earnings tied to operating sites, signed contracts and verbal awards.
The distinction matters because Archrock is paying for expansion as well as an existing business. The rest of the earnings forecast depends on projects still in development, with customers identified and discussions underway.
There is tangible support for the plan. HiVolt's initial power contracts run for five to eight years, with capacity-based payments designed to provide recurring revenue. It also has equipment on order sufficient for the forecast growth.
Access to more than 500 megawatts of generation equipment gives it room to expand. That is procurement access, rather than a fleet already producing that much electricity. Archrock expects more than 95% of HiVolt's 2028 adjusted EBITDA to come from upstream and midstream oil and gas customers.
The quoted multiple uses future profit
Archrock puts the transaction at about 6.1 times the midpoint of HiVolt's forecast 2028 adjusted EBITDA. Its calculation includes the $415 million upfront price and the portion of an incentive payment paid through 2028. It does not value the purchase against current earnings.
The base price is subject to adjustments, including working capital and qualifying capital spending before closing. A separate incentive plan could pay employees up to $35 million, tied to performance in 2027 through 2029 and continued employment, with specified exceptions. Archrock expects to record those payments as compensation expense.
Borrowing comes before the projected earnings
The financing presentation provides for a $425 million draw on Archrock's revolving credit facility: $415 million for the upfront payment and $10 million for transaction fees and expenses.
Archrock had reduced its reported leverage ratio, a measure of debt relative to earnings, to 2.5 times at September 30, from 3.1 times a year earlier. It expects the deal to leave leverage within its 3.0 to 3.5 times target range and to reach about 3.0 times by the end of 2027.
The acquisition brings longer power contracts and a customer base close to Archrock's existing compression business. Turning awarded opportunities into operating projects will determine how much of the 2028 profit forecast becomes available to support the larger debt load.
The Archrock company profile records its latest results, borrowing capacity and the proposed HiVolt transaction.